
A good CIBIL score can open the door to easier loan approvals, lower interest rates, higher credit card limits, and better financial opportunities. However, many people in India struggle to build their credit score because they either have no credit history or don’t know how credit scoring works.
One of the simplest and most effective ways to build a strong CIBIL score is through responsible credit card usage. When used correctly, a credit card acts as a financial tool that helps demonstrate your repayment discipline to credit bureaus.
Whether you are a student, salaried employee, freelancer, or first-time borrower, understanding how to build your CIBIL score using a credit card can significantly improve your financial future. This guide explains everything in simple English for Indian beginners.
What is a CIBIL Score?
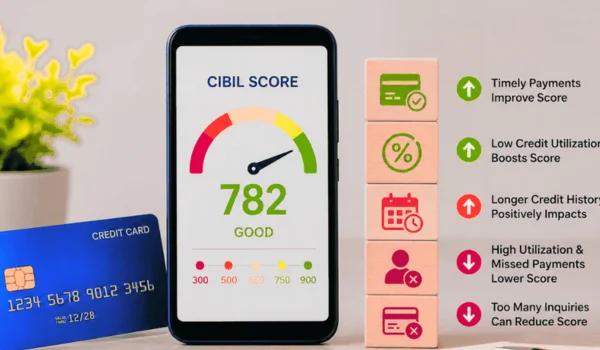
A CIBIL score is a three-digit number that represents your creditworthiness.
The score generally ranges from 300 to 900.
CIBIL Score Range
| Score Range | Credit Health |
| 800 – 900 | Excellent |
| 750 – 799 | Very Good |
| 700 – 749 | Good |
| 650 – 699 | Fair |
| Below 650 | Poor |
A higher score improves your chances of getting:
- Personal loans
- Home loans
- Car loans
- Premium credit cards
- Better interest rates
How Does a Credit Card Help Build CIBIL Score?
Whenever you use a credit card, your bank reports your repayment behavior to credit bureaus.
The bureau tracks:
- Payment history
- Credit utilization
- Outstanding balances
- Credit age
- New credit applications
Responsible usage helps improve your score over time.
How Credit Card Usage Impacts CIBIL Score
- Payment History
This is one of the most important factors.
Positive Impact
- Paying bills on time
- Paying full outstanding amount
Negative Impact
- Late payments
- Missed payments
- Defaults
- Credit Utilization Ratio
Credit utilization means how much of your credit limit you use.
Example
| Credit Limit | Spending | Utilization |
| ₹1,00,000 | ₹20,000 | 20% |
| ₹1,00,000 | ₹80,000 | 80% |
Experts recommend maintaining utilization below 30%.
- Credit History Length
The longer you maintain a credit card responsibly, the better it is for your credit score.
- Credit Mix
Having both:
- Credit cards
- Loans
can improve your overall credit profile.
- New Credit Applications
Applying for too many cards or loans in a short period may temporarily lower your score.
Eligibility to Build CIBIL Score Using a Credit Card
Anyone with a credit card can start building a CIBIL score.
| Criteria | Requirement |
| Active Credit Card | Yes |
| Regular Usage | Recommended |
| Timely Payments | Essential |
| Credit Reporting | Card issuer must report to bureaus |
Best Credit Cards for Building CIBIL Score
Beginners can consider:
| Card Type | Suitable For |
| Secured Credit Cards | No credit history |
| FD-Based Credit Cards | Students and beginners |
| Entry-Level Credit Cards | Salaried individuals |
| Lifetime Free Credit Cards | Budget-conscious users |
| Add-On Credit Cards | Family members starting credit history |
Benefits of Building CIBIL Score with a Credit Card
- Easier Loan Approval
Banks prefer borrowers with strong credit scores.
- Lower Interest Rates
Higher scores may help secure better loan terms.
- Higher Credit Limits
Banks are more likely to increase limits for responsible users.
- Premium Credit Card Eligibility
Good scores improve access to premium cards.
- Better Financial Reputation
A strong credit profile enhances overall financial credibility.
Fees & Charges Related to Credit Cards
Although building a CIBIL score is free, card charges may apply.
| Charge Type | Typical Range |
| Joining Fee | ₹0 – ₹1,000+ |
| Annual Fee | ₹0 – ₹5,000+ |
| Interest Rate | 30% – 48% per annum |
| Late Payment Fee | ₹100 – ₹1,500+ |
| Cash Withdrawal Fee | 2.5% – 3.5% |
| Foreign Currency Markup | 2% – 4% |
| GST | Applicable |
Reward Features While Building Credit Score
A credit card not only helps build a CIBIL score but can also provide rewards.
| Reward Feature | Benefit |
| Cashback | Savings on purchases |
| Reward Points | Redeemable for gifts and vouchers |
| Fuel Benefits | Fuel surcharge waiver |
| Shopping Discounts | Merchant offers |
| Travel Benefits | Lounge access and travel rewards |
| Welcome Bonuses | New user benefits |
Good vs Bad Credit Card Habits
| Good Habits | Bad Habits |
| Pay bills on time | Missing due dates |
| Keep utilization below 30% | Maxing out credit limit |
| Monitor statements | Ignoring bills |
| Use card regularly | Keeping card inactive |
| Maintain old accounts | Closing old cards unnecessarily |
Pros and Cons of Using Credit Cards to Build CIBIL Score
| Pros | Cons |
| Builds credit history | Risk of overspending |
| Improves loan eligibility | High interest on unpaid balances |
| Helps achieve higher scores | Late payments hurt score |
| Earn rewards while building credit | Requires financial discipline |
| Easy to track progress | Excessive applications can reduce score |
Step-by-Step Guide to Build CIBIL Score Using a Credit Card
Step 1: Get Your First Credit Card
Choose:
- Secured credit card
- FD-backed credit card
- Entry-level credit card
Step 2: Make Small Regular Purchases
Examples:
- Grocery bills
- Fuel expenses
- Utility payments
- Mobile recharges
Step 3: Keep Utilization Below 30%
Avoid using the full credit limit.
Step 4: Pay Full Bill Every Month
This is the fastest way to build a healthy credit profile.
Step 5: Enable Auto-Pay
Automatic payments reduce the risk of missing due dates.
Step 6: Monitor Your Credit Score
Review your credit report periodically to track progress.
How Long Does It Take to Build a Good CIBIL Score?
The timeline depends on your financial behavior.
| Period | Expected Outcome |
| 3–6 Months | Initial credit history established |
| 6–12 Months | Score begins improving |
| 12–24 Months | Strong credit profile possible |
| 24+ Months | Excellent score achievable with disciplined usage |
Tips to Maximize CIBIL Score Growth
Pay Before Due Date
Never delay payments.
Keep Utilization Low
Less than 30% is ideal.
Use One Primary Credit Card
Avoid managing too many cards initially.
Avoid Cash Withdrawals
Cash advances can increase debt and charges.
Check Credit Report Regularly
Correct any reporting errors immediately.
Maintain Long-Term Credit Relationships
Older accounts positively impact your score.
Common Mistakes to Avoid
Paying Only Minimum Due
This increases interest costs and debt burden.
Missing Due Dates
Even one missed payment can significantly affect your score.
Applying for Multiple Credit Cards Together
Too many applications create multiple hard inquiries.
Frequently Closing Old Cards
Older accounts contribute positively to credit history length.
Using Full Credit Limit Every Month
High utilization ratios may negatively affect your score.
Expert Tips for Indian Beginners
- Start with a secured or lifetime free card if needed.
- Use the card every month, even for small transactions.
- Maintain utilization between 10% and 30%.
- Pay the entire bill, not just the minimum due.
- Avoid taking unnecessary debt.
- Track your CIBIL score every few months.
Conclusion
A credit card is one of the most powerful tools for building a strong CIBIL score in India. By making regular purchases, maintaining low credit utilization, and paying bills on time, you can steadily improve your credit profile and unlock better financial opportunities.
The key is consistency and discipline. A well-managed credit card not only helps you build a score above 750 but also provides rewards, cashback, and financial flexibility along the way. If you’re just starting your credit journey, using a credit card responsibly can be the foundation of a healthy financial future.
Frequently Asked Questions (FAQs)
Q: Can a credit card improve my CIBIL score?
A: Yes. Responsible credit card usage and timely payments can significantly improve your CIBIL score over time.
Q: How much credit card utilization is ideal?
A: Most experts recommend keeping utilization below 30% of your total credit limit.
Q: How long does it take to build a good CIBIL score?
A: A noticeable improvement may take 6–12 months, while a strong credit profile often takes 1–2 years of responsible usage.
Q: Does paying the minimum due improve my score?
A: While it avoids default, paying only the minimum due can lead to higher interest charges and is not ideal for long-term credit health.
Q: Which credit card is best for beginners?
A: Secured credit cards, FD-backed cards, and entry-level lifetime free credit cards are popular options.
Q: Can students build a CIBIL score with a credit card?
A: Yes. Students can use secured credit cards, student credit cards, or add-on cards to start building credit history.
Q: Does closing a credit card affect CIBIL score?
A: It can. Closing older cards may reduce your average credit history length and affect your score.
Q: What is considered a good CIBIL score in India?
A: A score of 750 or above is generally considered good and improves your chances of loan and credit card approval.